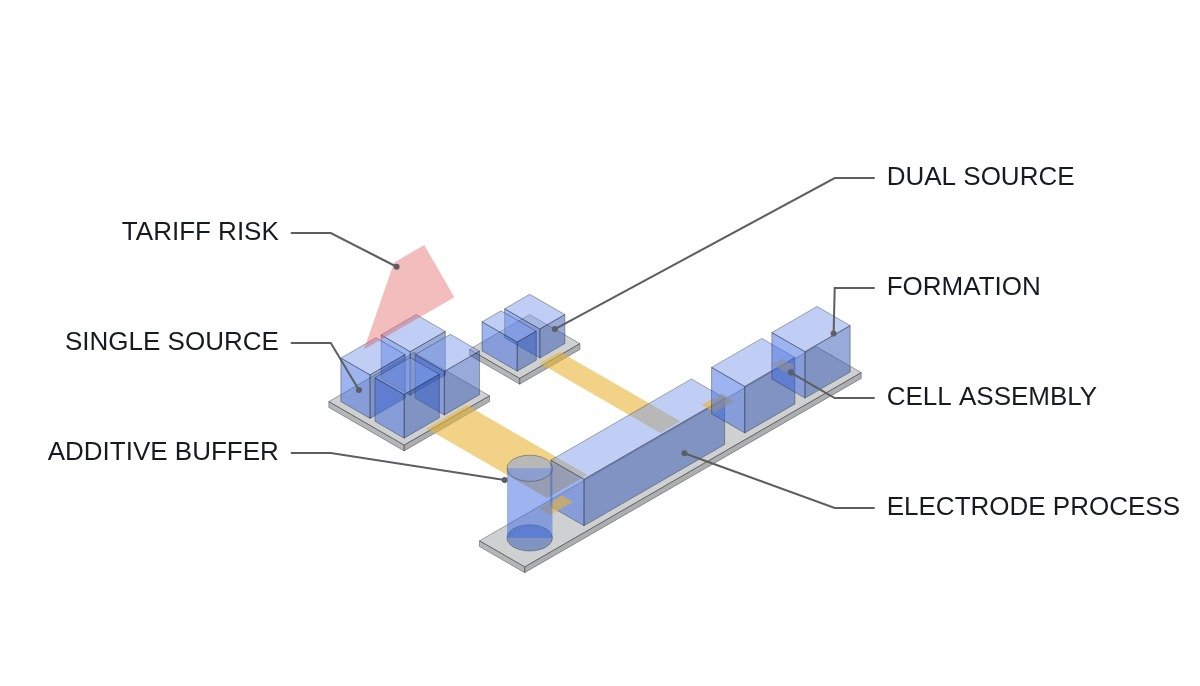
Domestic and non-China material dual-sourcing only pays off once the expected loss from supply-disruption risk driven by tariffs and export controls exceeds the added cost of diversification. Up to that point, a China-dependent supply chain remains the rational choice when cost-competitiveness is the deciding factor.
Where it pays off — the zone where geopolitical risk outweighs the cost gap
About 40% of LG Energy Solution’s core suppliers are currently Chinese firms, and China dependence runs high across cathode, anode, separator, and electrolyte materials alike. As US and European import/export controls tighten and tariffs are imposed, the production-line-stoppage loss from a supply disruption comes to exceed the added cost of dual-sourcing. In this zone, a shift to domestic/non-China materials is justified as an insurance-type investment — as in the case of Group14 and SK fully acquiring their domestic silicon-anode joint-venture plant to build an independent production system.
Where it doesn’t pay off — the zone where cost-competitiveness comes first
Dual-sourced domestic/non-China materials still lack economies of scale, so unit cost runs higher than Chinese-made material, and for some specialty additives Chinese suppliers are effectively the only ones with proven yield. Under these conditions, as long as the probability of supply disruption stays low, maintaining the cost-advantaged China-dependent supply chain is favorable on a total-cost basis. SK On signing a long-term high-nickel cathode supply agreement with China’s Dangsheng Technology, and discussing an additional 110,000-ton supply for 2026–2028, illustrates this judgment.
Comparison table
| Item | China-dependent supply chain | Domestic/non-China dual-sourcing |
|---|---|---|
| Unit cost | Low (economies of scale) | Relatively high |
| Supply stability | Vulnerable to regulation/tariffs | Lower geopolitical risk |
| Lead time | Stable (established system) | Early-stage scale-up delay |
| Representative case | SK On–Dangsheng Technology cathode supply agreement | Group14–SK silicon-anode JV plant acquisition |
The takeaway from the comparison table is selective dual-sourcing, not a wholesale switch. A staged approach is realistic: leave irreplaceable specialty additives on the Chinese supply chain while shifting general-purpose materials to domestic/non-China sources first.
Boundary condition
Where the dual-sourcing cost is calculated to be larger than the tariff avoided, or where quality variance in the domestic/non-China substitute materials meaningfully lowers cell yield, the advantage of dual-sourcing flips. The single decision criterion is whether the expected loss — irreplaceability per item (number of suppliers) multiplied by the probability of a tariff/regulatory event — exceeds the added cost of dual-sourcing.
References
- LG Energy Solution battery-supplier overseas non-China ratio — The Elec (Korean)
- K-Battery, the materials war — Hankook Ilbo (Korean)